Retiring or Snowbirding in the Phoenix Metro: A Financial Planner's Guide | Eric Ravenscroft
Retiring or Snowbirding in the Phoenix Metro: a financial planner's guide, not a listing tour
Most guides to Arizona's 55+ communities are written by people who've never modeled a retirement cash-flow statement. This one is — and it starts with the question that actually determines whether this move works: is it your money or your calendar that should decide?
You've searched some version of two things to land here: "moving to the Phoenix Metro for retirement" or "spending winters in Phoenix without giving up your life somewhere else." They sound like different questions. Financially, they're the same question asked from opposite ends — and almost nobody writing about Arizona's active-adult communities is qualified to answer it from both directions at once.
I am, because I spent the first half of my career as a Director of Wealth Management before I became a REALTOR®. Most of what follows didn't come from touring model homes — it came from building retirement income projections, running domicile and residency scenarios, and watching which financial decisions actually held up five and ten years later. The community comparisons are here too. But they come after the numbers, not instead of them.
Snowbird or full-timer? The question that comes before the community tour
Every 55+ community in the Valley will happily sell you a home either way. Only one of the two paths is right for your specific balance sheet, and the difference isn't lifestyle — it's domicile, tax exposure, and cash flow.
"Snowbirding" means Arizona stays a second home: your legal domicile, income tax filing, and Social Security check all stay anchored to the state you're leaving each spring. "Retiring here" means Arizona becomes home in the eyes of the county assessor, the Department of Revenue, and eventually your estate plan. Both are completely legitimate — the mistake is picking a community before deciding which one you're actually doing.
The Snowbird
- Domicile
- Stays in your current state. Arizona property is legally a second home.
- Property tax class
- Class 4 — the standard rate, no Homeowner Rebate, no Senior Freeze eligibility while seasonal.
- Income tax exposure
- You remain taxed by your home state on wages, pensions, and investment income. Arizona only taxes Arizona-source income, most commonly rental income if you lease the home while away.
- Cash flow
- Two sets of carrying costs — insurance, utilities on a seasonal baseline, HOA dues, and either a property manager or a trusted neighbor watching the home.
- Best suited to
- Households not ready to leave family, doctors, or a business behind, but who want a genuine second life for four to six months a year.
The Full-Time Retiree
- Domicile
- Arizona becomes home — driver's license, voter registration, and where you actually spend most of the year.
- Property tax class
- Eligible for Class 3 once the home is genuinely owner-occupied (roughly 7+ months a year by Maricopa County's standard), plus the Homeowner Rebate and, later, the Senior Freeze.
- Income tax exposure
- A flat 2.5% state income tax replaces your prior state's rate entirely. Social Security is not taxed at any income level, and Arizona levies no estate or inheritance tax.
- Cash flow
- One household, one full-time budget — though often the larger, better-appointed home, since it's the only one you're funding.
- Best suited to
- Households ready to make the financial and legal move completely, not just the physical one.
Neither path is objectively "better" — I've built financial plans that favored each, for households with nearly identical net worth. What decides it is where the rest of your financial life already lives: your income sources, your family, your healthcare network, and how many years you realistically have left to keep two households running. That's a conversation, not a checklist, and it's the one most Arizona real estate content skips entirely in favor of a photo of a golf course.
"The property tax classification is real money. But for almost every client I've walked through this decision, it's a secondary factor — the domicile question is the one that actually moves the needle on their retirement plan." Eric Ravenscroft, CRS
Arizona's tax climate for retirees, in five numbers
This is the condensed version. If property classification, the Senior Freeze, or Arizona's income tax rules are the piece you actually need to model, I've published a full breakdown of Class 3 vs. Class 4 status separately — worth reading before you write an offer.
A household bringing $120,000 in taxable retirement income from a state taxing it at roughly 6% pays about $7,200 a year there — versus about $3,000 at Arizona's flat 2.5%. That's over $80,000 across two decades, before compounding, and before the property tax and estate-tax differences are even added in.
This is illustrative, not a projection of your return — a licensed CPA should model your specific numbers, or start with our free calculators to run your own. Every one of these figures also interacts with your broader financial picture; see our complete real estate tax strategy guide or the full Arizona snowbird property tax guide →
Where snowbirds and retirees actually buy: 10 communities, compared honestly
Community choice is a financial decision as much as a lifestyle one. HOA structure, resale liquidity, and whether a community even permits renting the home out while you're away all belong in the same spreadsheet as the price. Here's how the Valley's ten most-searched 55+ communities actually compare — alphabetically, so nothing here reads as a ranking.
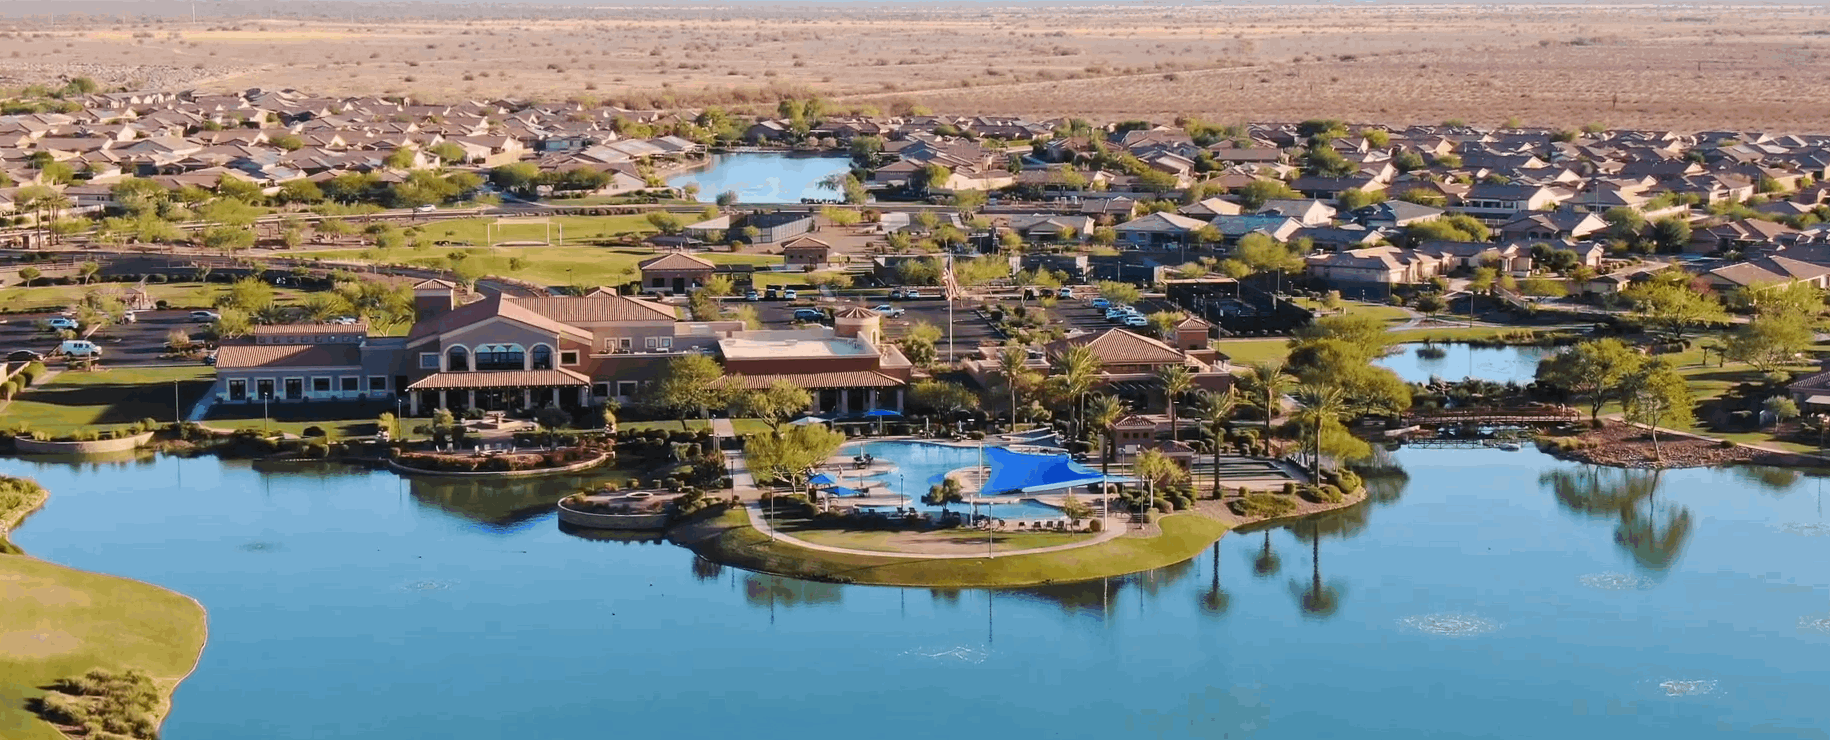
CantaMia
A younger, more architecturally distinctive West Valley community built within the larger master-planned Estrella, with golf access borrowed from its neighbor rather than its own course. Popular with buyers who want resort amenities without a full country-club premium.
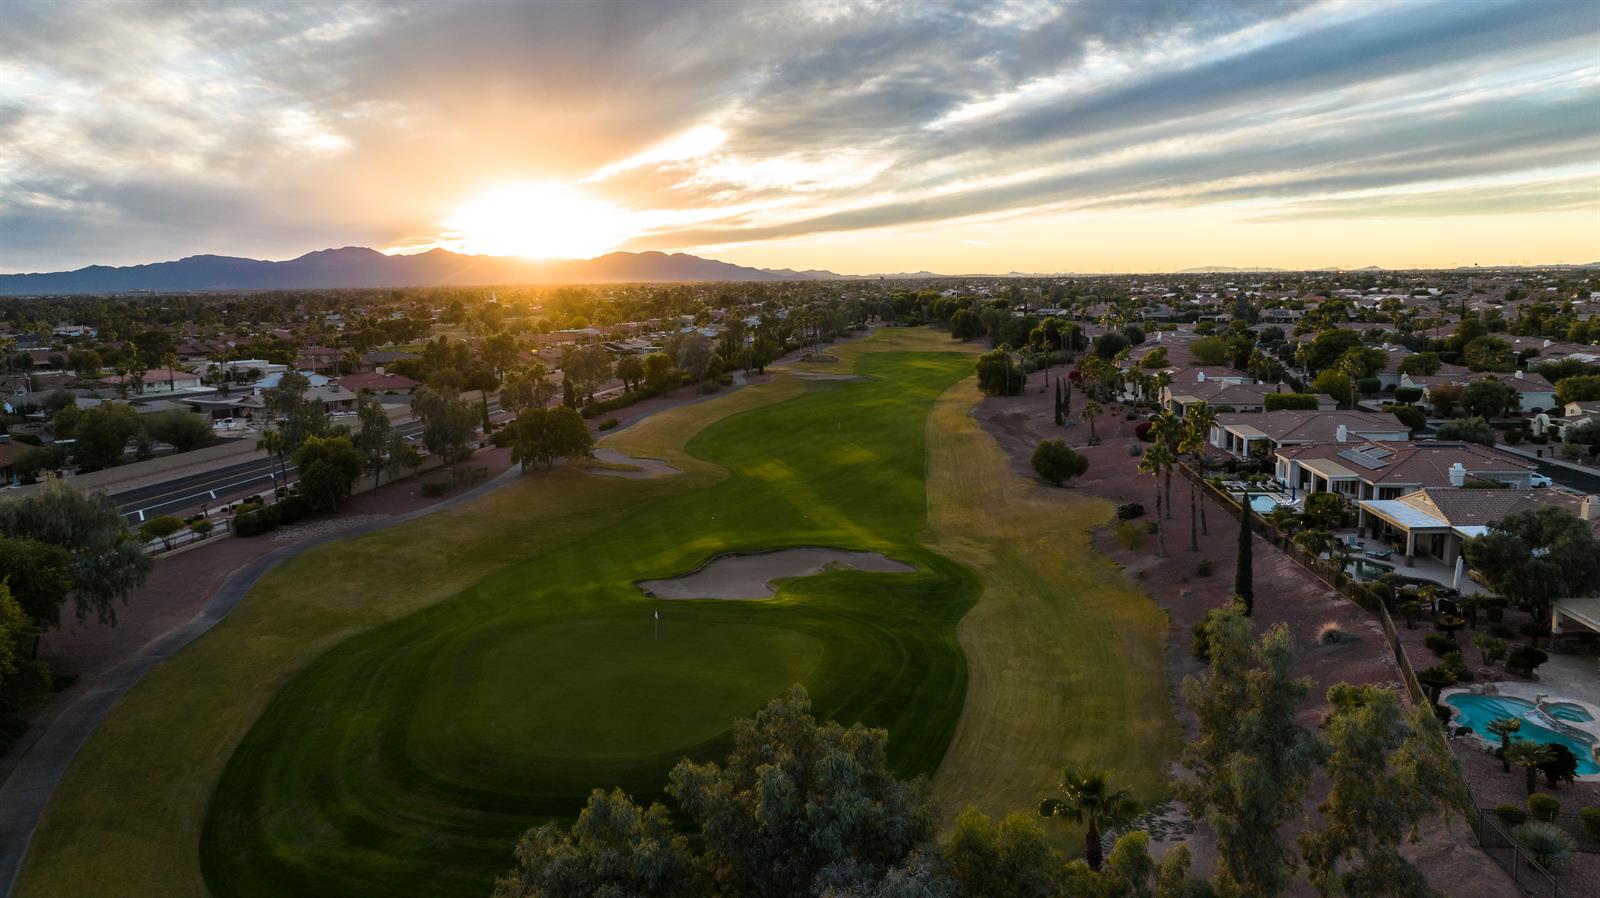
Corte Bella
A Del Webb country-club community built between 2003 and 2007, smaller and quieter than its Sun City neighbors, with one 18-hole course and a strong resale track record — it has repeatedly led Valley 55+ communities in year-over-year appreciation.
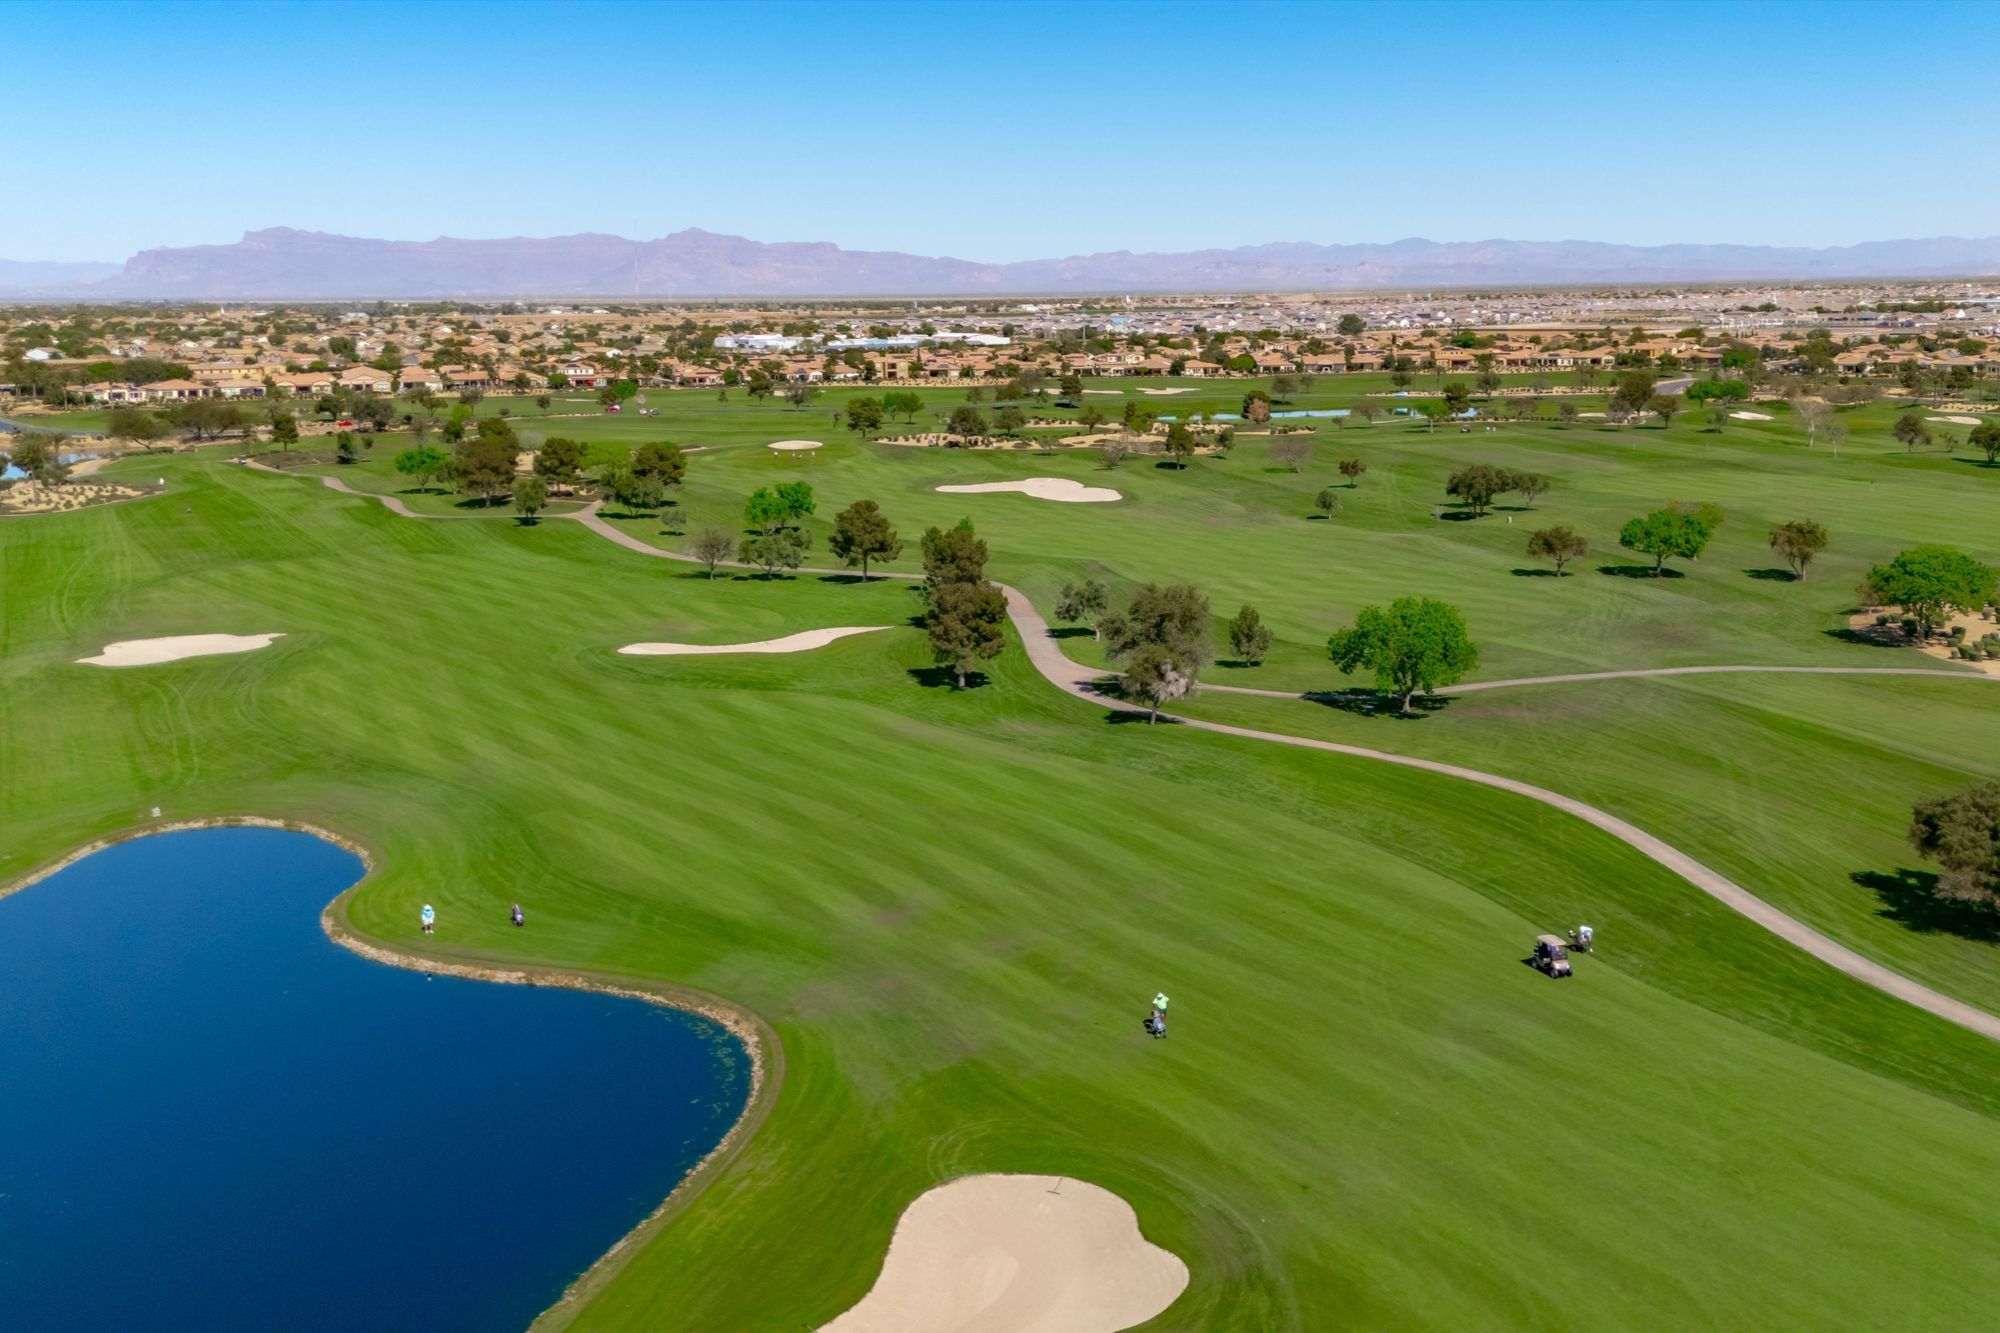
Encanterra, a Trilogy Resort Community
Shea Homes' resort flagship, built around two clubhouses — the 60,000-square-foot La Casa and the more intimate Algarve — an 18-hole Tom Lehman-designed course, and a mandatory country-club social membership baked into ownership. The most resort-dense option on this list.
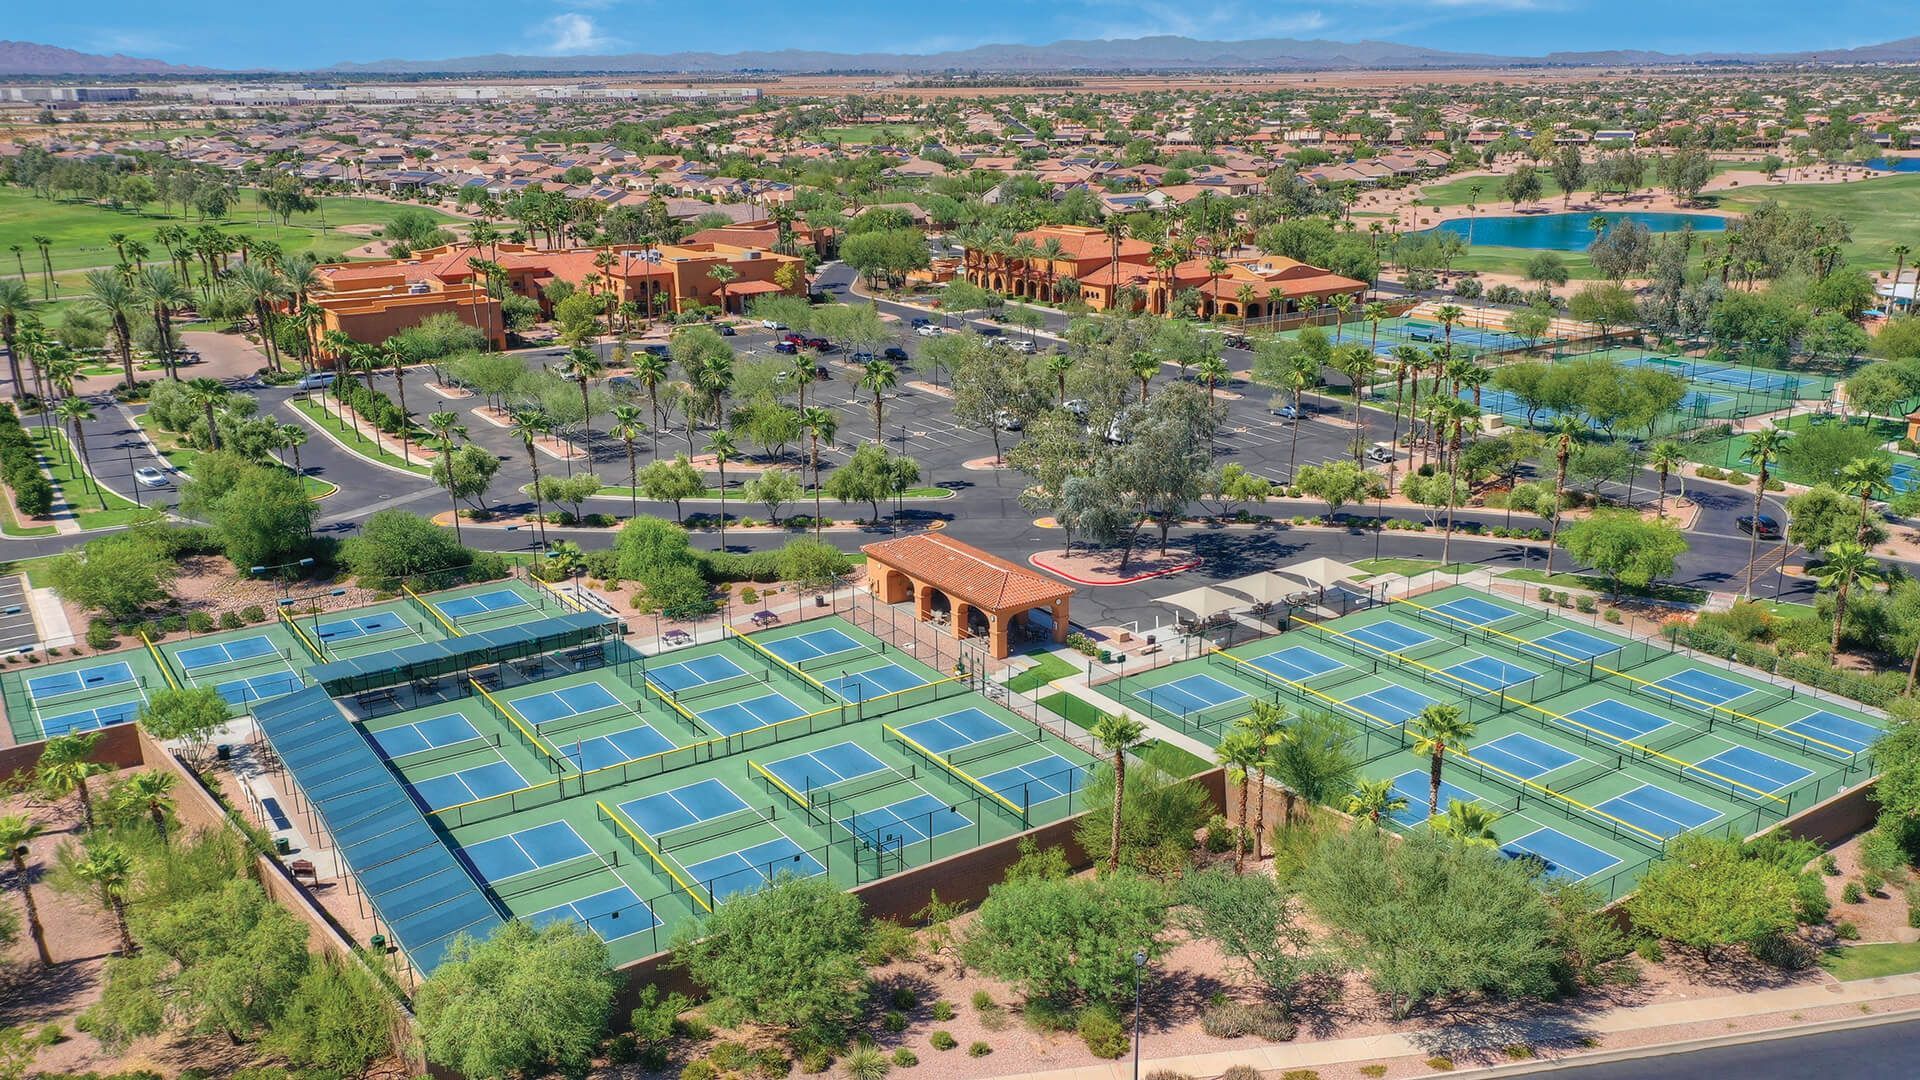
PebbleCreek
A 2,300-acre Robson Communities development with three golf courses, 36-plus pickleball courts, and 60-plus floor plans across both resale and ongoing new construction — one of the largest and most amenity-dense communities in the Valley.
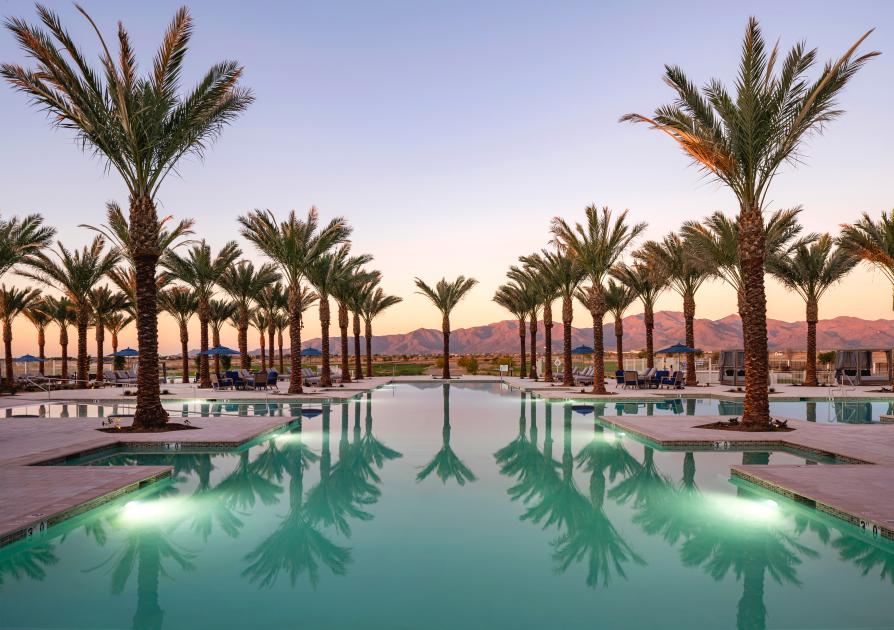
Sterling Grove
Toll Brothers' newest and most upscale entry, still actively building since 2020, blending 55+ and all-ages sections around a private golf club. Posted the strongest median-value appreciation of any community on this list through the first half of 2026.
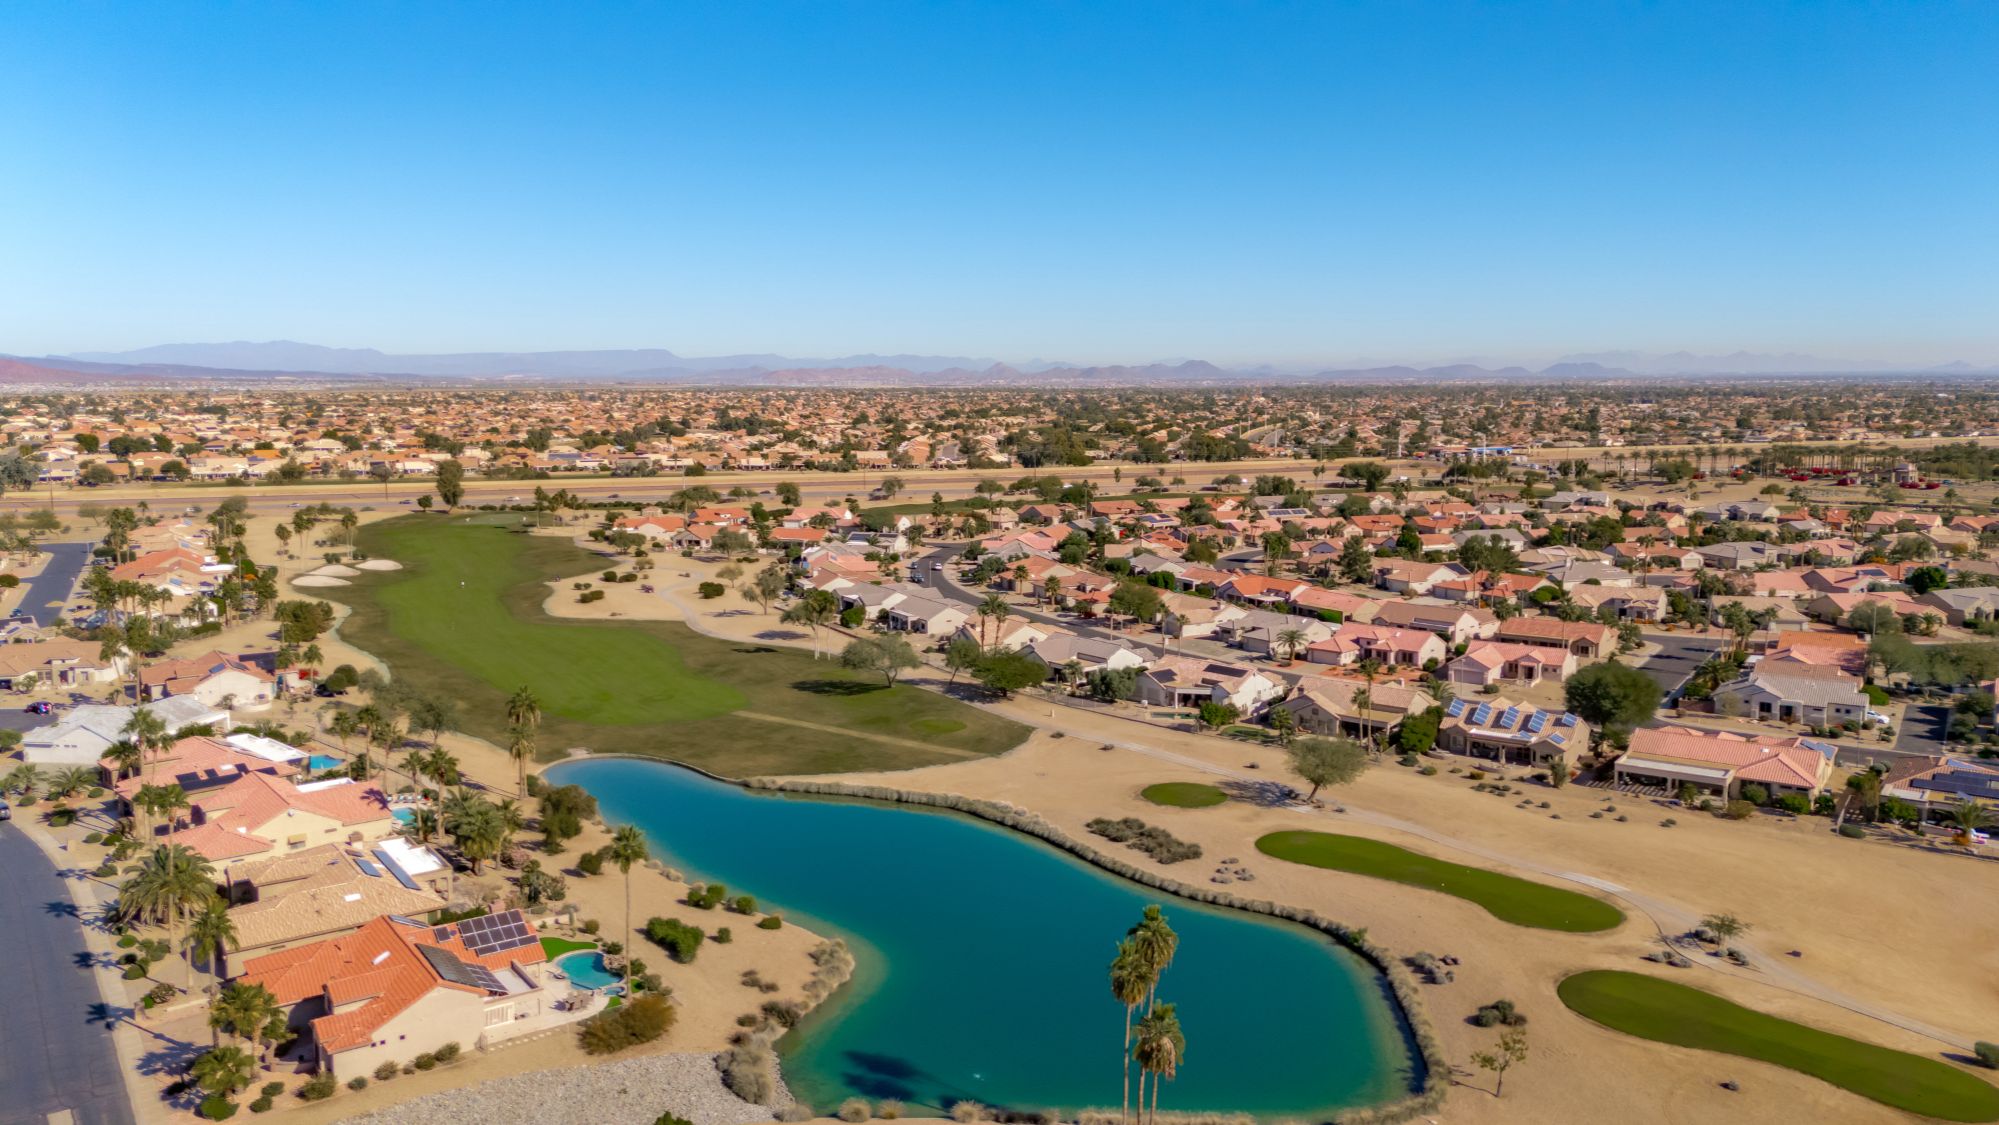
Sun City Grand
Del Webb's second-generation Sun City, built 1996–2005, with four 18-hole courses, five pools, and a lower minimum age than its predecessors — a common landing spot for couples where one spouse hasn't hit 55 yet.
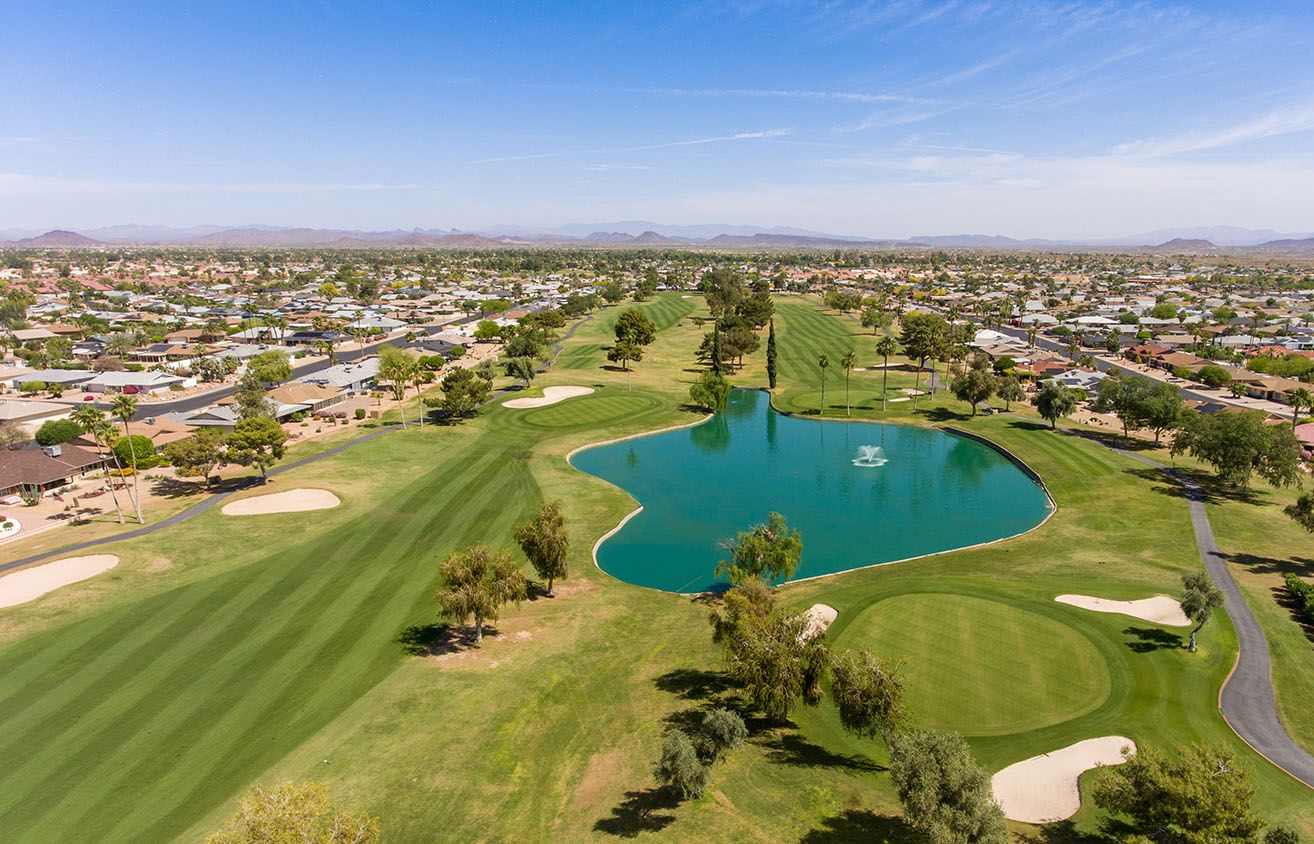
Sun City West
Built out 1978–1997 across 7,100 acres with nine golf courses, four recreation centers, and 120-plus floor plans. Consistently among the highest-rated communities on this list for resident satisfaction, with low carrying costs relative to its amenity base.
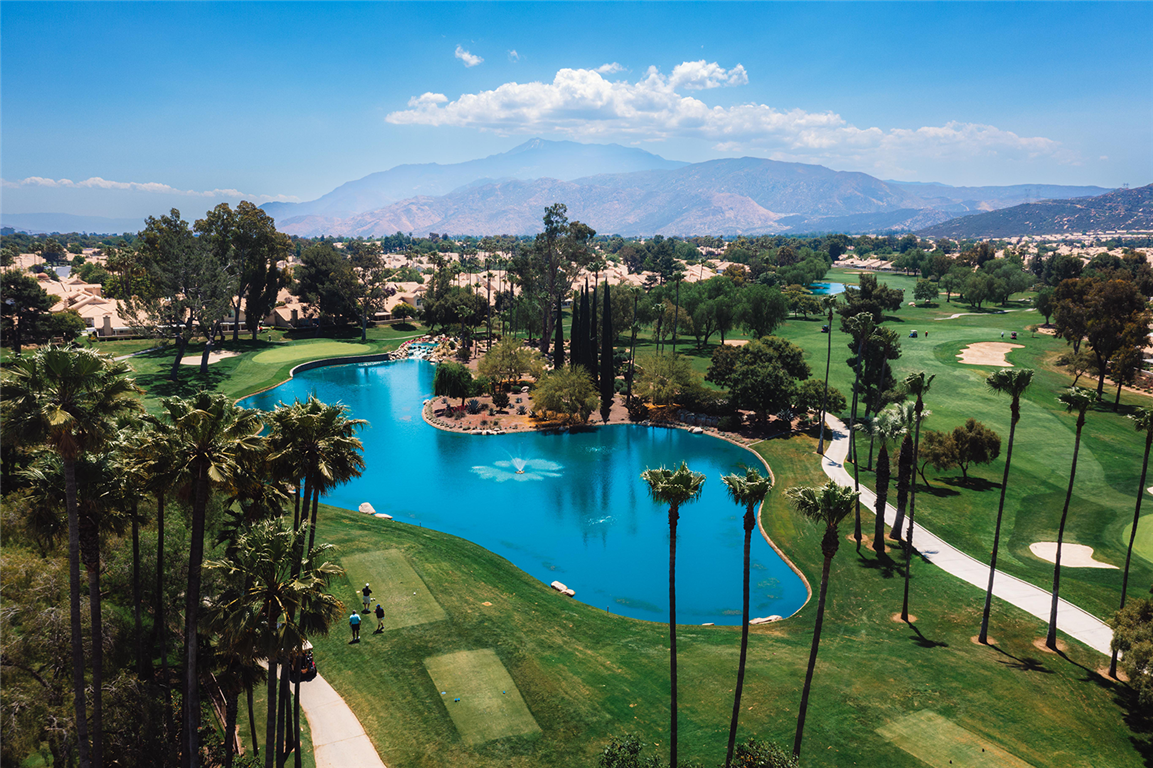
Sun Lakes
A Robson Communities master plan of five distinct country-club neighborhoods — Sun Lakes CC, Palo Verde, Cottonwood, Ironwood, and Oakwood — each with its own golf course, HOA, and price point, giving buyers a genuine range within one address. Roughly 20 minutes from Sky Harbor.
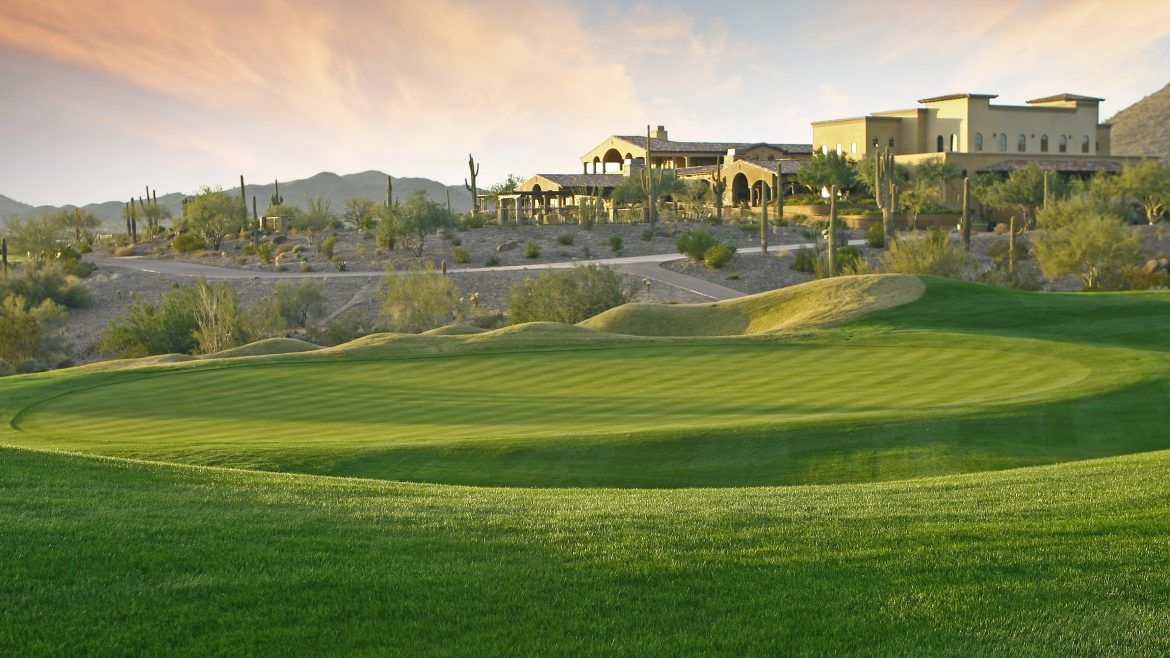
Trilogy at Vistancia
Shea Homes' original Trilogy, built 2004–2023 within the larger master-planned Vistancia, with one golf course, four restaurants, and a resale-only market that has been one of the steadiest performers in the Valley's active-adult segment.
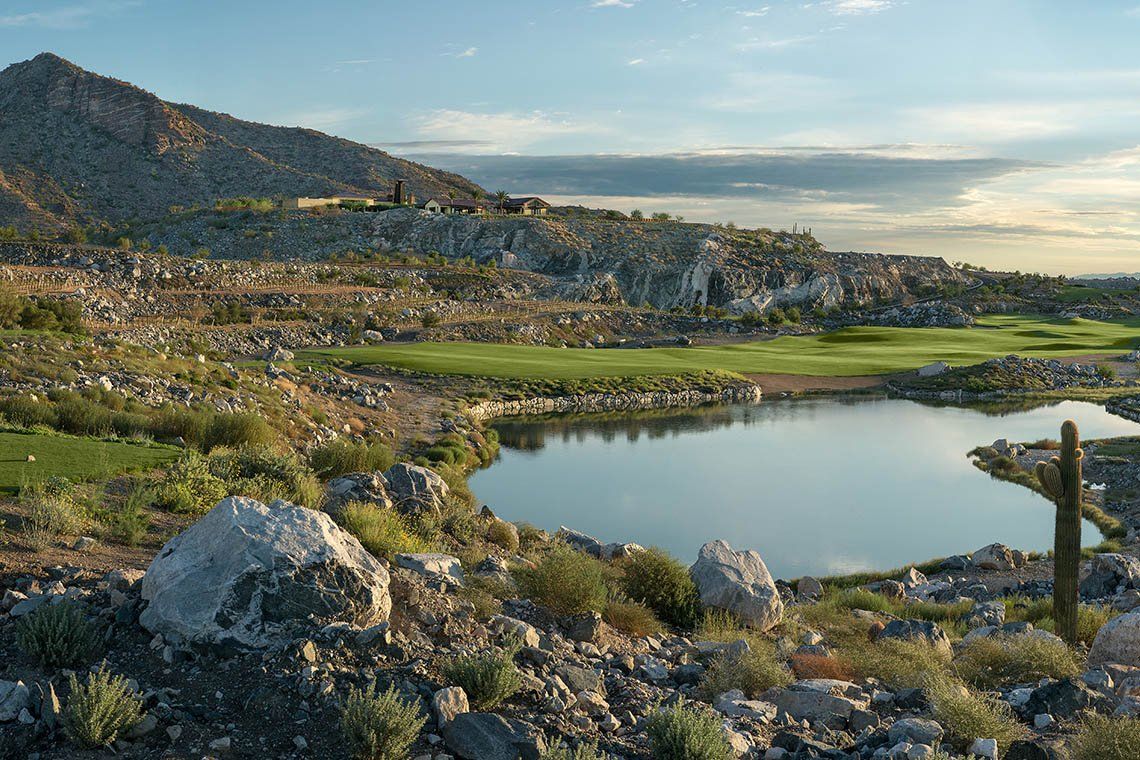
Victory at Verrado
The active-adult neighborhood within the larger Verrado master plan, offering both resale and ongoing new construction, four pools, and access to Verrado's own golf course and Main Street shopping district — walkability few other communities on this list can match.
| Community | Submarket | Age restriction | Approx. HOA/mo | Gated | Golf courses |
|---|---|---|---|---|---|
| CantaMia | Goodyear | 40+ new / 55+ resale | ~$350 | Yes | Shared access |
| Corte Bella | Sun City West | 45+ | ~$217 | Yes | 1 |
| Encanterra | Queen Creek | 55+ enclave | Membership-based | Yes | 1 |
| PebbleCreek | Goodyear | 40+ | ~$272 | Yes | 3 |
| Sterling Grove | Surprise | 55+ & all-ages | ~$175 + rec | Yes | 1 (private) |
| Sun City Grand | Surprise | 45+ | ~$160 | No | 4 |
| Sun City West | Sun City West | 55+ | ~$100 | No | 9 |
| Sun Lakes | Chandler | 55+ | ~$115–$175 | Mixed | 5+ (across sections) |
| Trilogy at Vistancia | Peoria | 55+ resale | ~$340 | Yes | 1 |
| Victory at Verrado | Buckeye | 55+ | ~$258 | Partial | Shared access |
Figures are approximate, general-market ranges as of 2026 and vary by section, home size, and whether recreation or club fees are billed separately. Confirm current HOA disclosures and CC&Rs directly with each community before writing an offer. Sterling Grove, PebbleCreek, and CantaMia all still have active new-construction phases — see our full guide to new construction homes and developments across the Valley for current builder pricing and incentives.
The piece almost nobody else in this space talks about
Comparing HOA fees and pool counts is the easy part. The harder — and more consequential — question is whether the whole move actually strengthens your retirement plan, and that requires someone who can read both a purchase contract and a cash-flow projection.
Fifteen years ago I was building retirement income models and running tax scenarios as a Director of Wealth Management, before a licensed real estate credential ever entered the picture. That background is why this guide leads with domicile and tax exposure instead of granite countertops, and it's why my clients get something most Phoenix Metro agents simply don't offer: a genuine complimentary financial evaluation of the move itself, alongside the transaction, not instead of it.
Domicile & residency planning
Modeling exactly what full-time relocation changes — income tax, property classification, voter and licensing requirements — versus what stays the same if you snowbird instead.
Two-household cash-flow modeling
A real projection of what running an Arizona home alongside your current one does to monthly cash flow, not a rule-of-thumb estimate — including our listing strategy for your departure-state home if selling it outright turns out to be the right call.
Social Security & RMD coordination
Timing Social Security claims and structuring Required Minimum Distributions around a move that may change your effective tax rate significantly.
Property tax classification strategy
Understanding Class 3 vs. Class 4 status, the Senior Freeze timeline, and how each interacts with your specific residency plan.
Seasonal rental income analysis
If you'll rent the home out while you're away, a full picture of Transaction Privilege Tax, depreciation, and net income — before the first booking. See how much income your property could generate to run a first estimate.
Estate & step-up basis planning
How owning property across two states affects your estate plan, and how Arizona's community-property step-up in basis can benefit heirs if you domicile here.
All of this is offered complimentary alongside your real estate transaction — the same comprehensive planning process I'd have charged for as a wealth manager, now built into how I represent buyers and sellers across the Phoenix Metro. It isn't fiduciary investment advice, and I always recommend confirming specifics with your own CPA or estate attorney — but it means the community decision comes after the financial one is actually sound, not instead of it.
A framework: five questions to answer before you buy
Use this before you fall in love with a floor plan. Every one of these questions changes the answer to "which community" — sometimes entirely.
Where will your domicile actually be, legally?
Not where you'd like it to be someday — where your driver's license, voter registration, and majority of the calendar year will genuinely sit. This single answer determines your entire tax and property-classification picture.
What does running two households do to your cash flow?
Model it with real numbers — HOA dues, insurance on both properties, utilities, travel between them, and a property manager or trusted contact for the home while you're gone.
Will you rent the Arizona home while you're away, and does that change your tax picture?
Renting can offset carrying costs meaningfully, but it introduces Transaction Privilege Tax obligations, HOA rental restrictions, and depreciation questions that belong in the purchase plan, not an afterthought. If income property is genuinely part of the plan, our Arizona investment property guide breaks down realistic cap rate and cash-on-cash return expectations for the Phoenix Metro.
Does the community's fee structure match how many months a year you'll actually use it?
A mandatory country-club membership makes sense if you'll golf four months a year. It's a very different value proposition if you're there six weeks.
What happens to your estate plan once you own property in two states?
Probate, basis step-up, and trust structuring all look different depending on where each property sits and where you're domiciled — worth coordinating with your estate attorney before closing, not after.
From clients who made the move
Verified 5-star reviews from Eric's Google Business profile — reproduced in full, with a link back to each reviewer's public Google Maps profile.
We were very happy that we went with Eric to purchase a second home in Arizona. Being from out of state and not knowing much about the housing market was daunting but Eric made it so easy. He had a lot of useful tools for us to use, and when it was time to fly out and view homes he maximized our day so we could get a lot in. He was professional, very knowledgeable, and answered any questions we had quickly. Would highly recommend Eric to anyone looking to purchase a home in this area.
We've been working with Eric for the past few months after relocating to Arizona from another state and deciding to purchase a home here. From the very beginning, Eric provided invaluable guidance and support throughout the entire process. His knowledge of the market, financing, current trends, and future real estate developments is truly impressive. Since we were building a new home, the process came with additional challenges and required coordinating with multiple people — thanks to Eric's expertise, we were able to identify important details in the construction process we otherwise might have missed. Today we are proud owners of a brand-new home.
Working with Eric was an outstanding experience from start to finish. From our earliest conversations, he demonstrated an exceptional ability to quickly understand our investment criteria and long-term objectives. As out-of-state buyers, we relied heavily on his market expertise, and his insights — both at the location level and the individual property level — were consistently thoughtful, data-driven, and candid. We encountered a particularly challenging mortgage process, and he worked tirelessly to ensure our interests were protected at every step. We look forward to working with him again and would recommend him without hesitation.
Moving from one state to another is never easy, especially when I had been in the same house for 22 years. Eric was recommended to us and we could not have been any happier with the service he provided. He was always very responsive to our needs, did a lot of legwork we could not, and made this a very smooth and easy transition. We highly recommend him if you are in the market for a new home. His knowledge, customer service, and helpfulness cannot be beat.
Reviews shown are genuine, unedited client feedback reproduced from Eric's public Google Business profile with the reviewer's name as publicly posted. Individual results vary — past client experiences are not a guarantee of future results, and no compensation was provided in exchange for any review shown here. Read more on our full client testimonials page.
Not sure yet whether snowbirding or a full move is the stronger financial decision for you?
A 15-minute conversation — grounded in an actual financial plan, not a sales pitch — is usually enough to know which direction to take next.
Eric Ravenscroft, CRS
Top 1% REALTOR® across North America · Former Director of Wealth Management · The Ravenscroft Group at Real Broker
Arizona REALTOR® · License SA691304000 · Real Broker, LLC · Member, National Association of REALTORS®
Eric closed his career in institutional wealth management before becoming a REALTOR®, and built The Ravenscroft Group around a simple premise: real estate decisions are financial decisions, and retirees and snowbirds deserve an advisor who treats them that way. He has closed more than $100 million in residential sales, helped clients create over $150 million in long-term wealth, and holds more than 150 five-star Google reviews across the Phoenix Metro.

Eric is a preferred real estate partner for the nation's largest financial institutions — reinforcing his standing among the industry's most trusted advisory professionals for relocating and retiring clients.
Questions we hear on almost every call
Do I have to live in Arizona full time to buy in a 55+ community?+
No. Most Phoenix-area active-adult communities welcome part-year owners, and several — CantaMia, Victory at Verrado, Trilogy at Vistancia, and Sterling Grove among them — were largely built with seasonal buyers in mind. Age restrictions govern who can live in the household, not how many months a year you're physically present.
What's the real difference between snowbirding and becoming an Arizona resident for tax purposes?+
Owning a home here doesn't change your legal domicile. Snowbirding keeps your income tax filing and property tax classification anchored to your home state. Only when Arizona genuinely becomes where you spend most of the year, hold your license, and register to vote does the flat 2.5% income tax, the Social Security exemption, and Class 3 property status begin to apply.
Which Phoenix-area 55+ community is best for snowbirds specifically?+
It depends on budget, whether you plan to rent the home out while you're gone, and how much lock-and-leave simplicity you want. Sun City West and Sun City Grand carry the lowest costs for occasional use; Sterling Grove and Encanterra offer the newest, most amenity-dense product for buyers who want minimal upkeep and a resort feel.
How much does it cost to snowbird in the Phoenix Metro each year?+
Beyond the purchase price, expect HOA dues (roughly $100 to $450-plus a month depending on community), property tax at the Class 4 rate, utilities on a lower seasonal baseline while away, homeowner's insurance, and either a property manager or a trusted neighbor checking the home in the off months. A full cash-flow picture should be built before you buy.
Can I rent out my Arizona home while I'm away for the summer?+
Many communities allow long-term or seasonal rentals, though HOA rules vary and some age-restricted communities limit short-term stays. If you do rent it out, Arizona's Transaction Privilege Tax applies, and the activity can change your depreciation and tax picture — worth structuring correctly from day one.
Do I need to change my driver's license or voter registration to get Arizona's tax benefits?+
Generally, yes — domicile is established through a pattern of facts, and your license, voter registration, and where your doctors and bank accounts are all factor in. High-tax states of origin sometimes audit residency claims aggressively, so documentation matters if you're intentionally establishing Arizona as home.
How do I decide between renting for a season first vs. buying?+
A season of renting is genuinely useful if you're unsure which submarket or community style fits — it costs less than a wrong purchase. But it isn't necessary for everyone, particularly buyers who've vacationed in the Valley for years already and know their preferred area. This is worth a direct conversation about your specific situation.
Is now a good time to buy in a Phoenix 55+ community?+
Phoenix's active-adult segment has held value more steadily than the broader metro market in recent cycles, with resale-only communities showing particular resilience. Timing should be driven by your own financial readiness and each community's current inventory and incentives, more than by trying to call a market bottom — see our current Phoenix housing market updates for the latest data.
Categories
- All Blogs (318)
- Active Adult & 55 Plus Communities (16)
- Arizona Relocation Guides (29)
- Buyers (209)
- Financial Planning (60)
- General Real Estate (136)
- Income From Real Estate (58)
- Market Update (25)
- New Construction (28)
- News, Updates and Coming Soon (57)
- Real Estate Agent Financial Planning (22)
- Real Estate Investing (93)
- Sellers (105)
- Vacation and Short Term Rentals (45)
Recent Posts


About the Author
Eric Ravenscroft is a Top 1% REALTOR® across North America and one of Arizona’s most trusted real estate strategists. With 15 years of experience spanning real estate, wealth management, and investment planning, he helps clients make smarter, financially grounded decisions, from new construction and relocations to STR investments, 1031 exchanges, and long-term portfolio strategy.
Eric’s expertise has earned him industry recognition, Elite status with Real Broker, and features in major publications including the Wall Street Journal, MarketWatch, MSN, and Morningstar. Clients across the Greater Phoenix Metro rely on his clarity, strategic insight, and results-driven guidance.
Ready to make a confident real estate move? Call or text Eric today.