Selling Before You Buy: The Homeowner's Transition Playbook
Selling Before You Buy: The Homeowner's Transition Playbook
Seven proven ways to bridge the gap between the home you're leaving and the one you're not in yet — from bridge loans and rent-backs to the 2026 rule that lets you use market rent, not a signed lease, to offset your old mortgage.
Moving from one home to another sounds like a single transaction, but it's really two — and they rarely close on the same afternoon. Sell first and you risk having nowhere to live for a few weeks. Buy first and you risk carrying two mortgages at once. Almost every tool in this guide exists to soften one side of that trade-off.
Every strategy below answers one of two questions: how do I fund a purchase before my current home sells, or how do I keep a roof over my head after it does? The right answer depends on your equity, how fast homes move in your market, and how much financial slack you can tolerate for a few months.

Trusted By
Phoenix's Preferred Agent for
Leading Financial Institutions
Eric is a preferred real estate partner for USAA, Chase, SoFi, PennyMac, Citibank, Citizens, Huntington, Fifth Third, and other major institutions — institutions whose clients often face exactly this sell-versus-buy timing problem during a relocation.
Strategy comparison at a glance
Seven paths, seven very different risk profiles
| Strategy | Best when | Typical cost | Risk level |
|---|---|---|---|
| Rent-back after selling | You need extra weeks after closing to move | Rent to buyer, usually below market | Low |
| Bridge loan | Strong equity, home expected to sell in months | High — origination fees + elevated rate | Medium |
| HELOC / home equity loan | Arranged well before listing, solid equity | Moderate — standard equity-loan rates | Medium |
| Keep it, rent it (2026 rule) | You'd rather not sell at all | Appraisal/rent study; 6 mo. reserves if <12 mo. history | Low–Medium |
| Home sale contingency | Buyer's market, flexible seller | Low direct cost | Low, but often rejected |
| Non-contingent offer | Cash reserves to carry two homes | None upfront, high exposure | High |
| iBuyer / trade-in program | Speed and certainty matter most | Service fee, below-market offer | Low |
Sell first, then buy
The lowest-risk sequence, and still the most common
This is the safest route financially — you know your exact proceeds before committing to a new mortgage. Two tools make it work — and how you list matters too; see my listing strategy guide for how pricing and timing decisions affect everything downstream:
Negotiate a leaseback
After your home sells, rent it back from the buyer — often 30 to 60 days — while you close on the next place. Raise this with your agent before accepting an offer; it's part of the purchase contract, not an afterthought.
Pricing: typically set to cover the buyer's new PITI plus a small cushion, prorated daily — not a flat market rent. You'll also want your own short-term landlord or liability policy in place for the rent-back period; your homeowner's policy alone usually won't cover you as a tenant in a home you no longer own.
Extend the closing date
A longer close — 45 to 60 days instead of 30 — gives you runway to find and close on your next home without needing temporary housing at all.
Even with a rent-back or extended close, it's worth lining up a fallback — an extended-stay option or a family member's spare room — in case your next purchase takes longer than planned.
Buy first, then sell
Better for moving day, but it needs a financing bridge
This sequence avoids moving twice, but requires funding the new purchase before the old one closes. Four tools handle that gap:
Bridge loan
Short-term financing secured against your current home's equity, paid off once it sells. Most lenders will lend up to roughly 80% of your home's value. Interest-only, higher rate — a convenience tool, not a cheap one. Rates typically run several points above a standard mortgage — often in the 7–9% range depending on the lender and your equity position — and the loan is usually structured either as a second loan cross-collateralized against both properties, or as two separate loans your lender coordinates to close together.
Typically requires: 20%+ equity in your current home, a 680+ credit score, and combined loan balances under 80% of its value.
HELOC / home equity loan
Cheaper than a bridge loan if arranged in advance. The catch: most lenders won't approve one once your home is actively listed, so this has to happen months ahead. Rates are typically variable, tied to the prime rate, with an initial draw period — often 10 years — where you can borrow, repay, and re-borrow, followed by a repayment period where the balance amortizes and new draws aren't allowed.
Typically requires: a 680+ credit score and at least 15–20% equity remaining once the HELOC is in place.
Cash-out refinance
Pull equity out via refinance and apply it to the new purchase. Usually only worth it if the math still works for a short holding period — the least efficient option here. The biggest catch: you're resetting your entire mortgage to today's rate, not just borrowing against the cash-out portion — if your current rate is well below what's available now, refinancing can cost you more in the long run than a bridge loan or HELOC would.
"Buy before you sell" programs
Newer lender and fintech products that qualify you against projected sale proceeds, with financing that's paid off at closing — sometimes bundled with a guaranteed backup offer.
Not sure which of these fits your numbers?
Equity, timeline, and your target market all change the math. Let's walk through your specific move together.
New for 2026: using market rent to offset your old mortgage — no lease required
Fannie Mae Selling Guide Announcement SEL-2026-08, effective September 2, 2026
There's a seventh path worth knowing about: instead of selling your current home at all, you may be able to keep it, convert it to an Arizona investment property, and use that future rent to help qualify for the new mortgage — without ever signing a tenant to a lease first. Not sure what your property could realistically bring in? Start with this rental income estimate. If you're leaning that way, it's worth reading how this pairs with the tax side — see how a short-term rental conversion can unlock bonus depreciation.
On September 2, 2026, Fannie Mae changed how rental income from a departing residence gets documented for conventional loans. Lenders can use the new rules now, and every conventional lender must be using them by November 1, 2026.
Signed lease required
Using rental income from a departing residence required an already-signed lease with a tenant in place before closing — a hard requirement that often derailed the buy-first sequence entirely.
Market rent, appraisal-based
A lease is no longer permitted as documentation at all. Market rent — established via Form 1007 (1-unit), Form 1025 (2–4 unit), or a market analysis with at least three comparables — is required instead. 75% of that documented rent counts toward qualifying.
Offset only — never added income: regardless of landlord experience, this rental income can only offset the departing home's own PITIA payment — it's never added to your overall qualifying income. What landlord experience determines is reserves: with less than 12 months of documented property-management history, you'll need six months of PITIA reserves for the departing property, on top of whatever your new loan already requires. Individual lenders can still layer on their own overlays, so confirm with your specific lender how they're applying the update.
A quick note on financing variations: VA loans already worked this way and don't require a lease — expected rent offsets the old payment, with no landlord-history requirement, but it can't be added to income. Freddie Mac maintains its own separate guidelines, and any equivalent change there would come through its own Bulletin process.
These strategies in action
Real Phoenix-market scenarios, not hypotheticals
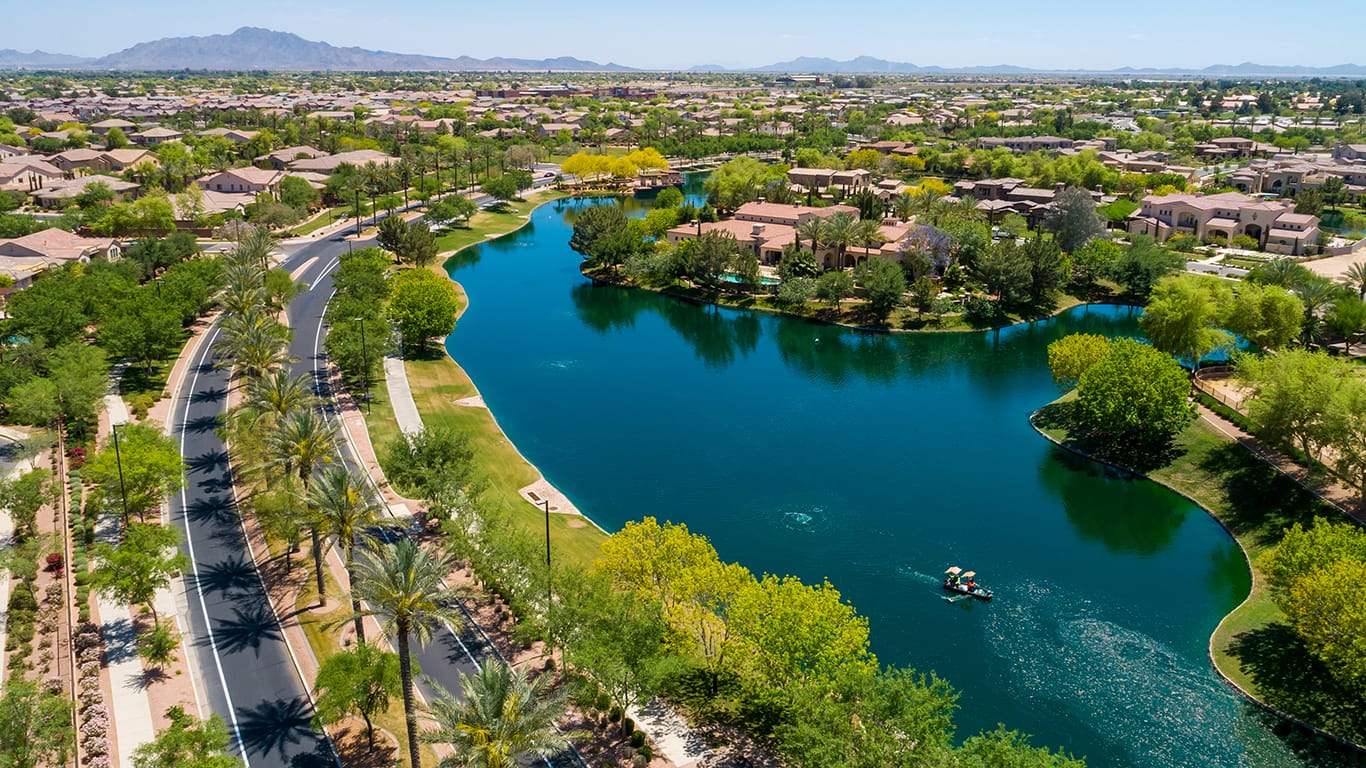
Bridge loan for an out-of-state relocation
A relocating family found their Arcadia home before their San Diego property had sold in a slowing market. A bridge loan against their San Diego equity let them move on their timeline.
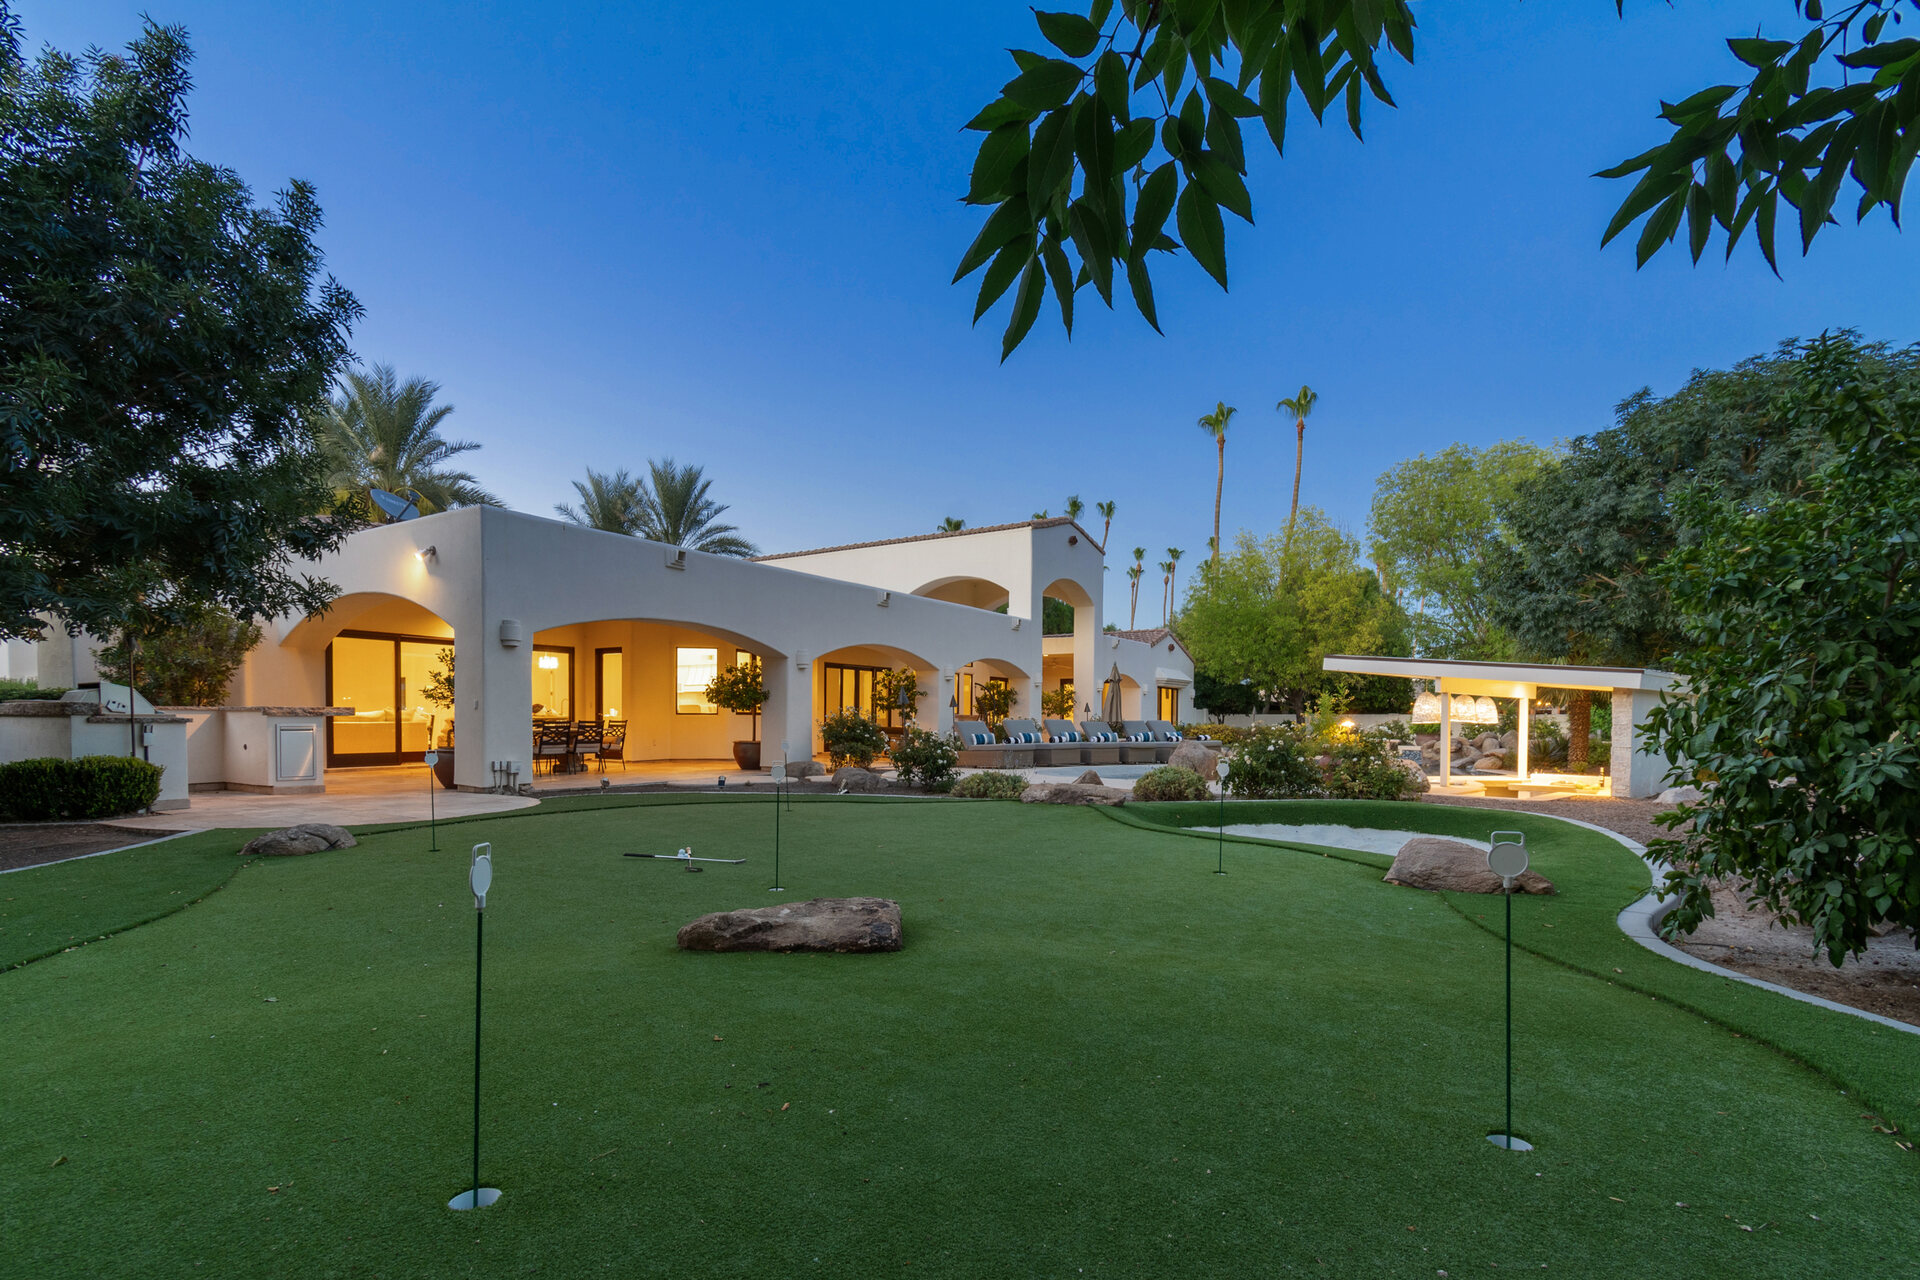
Bridge loan to compete without a contingency
A couple upgrading to Chandler used a bridge loan to make a clean, non-contingent offer in a competitive market — then sold their townhouse on their own timeline.
HELOC for a shorter hold period
A growing family only needed financing for six months before their Avondale home sold, so a HELOC's lower rate beat a bridge loan's higher one.
Renting instead of selling
A relocating family rented out their Seattle home rather than selling into an uncertain market, using that rental income to help qualify for a new Buckeye mortgage.
Rent-back to avoid a double move
A downsizing seller closed on their North Scottsdale home first, then rented it back from the buyer for 45 days while their Old Town Scottsdale condo finished closing — no temporary housing needed.
Cash-out refinance to bridge a short gap
To show how this compares to a bridge loan: a homeowner refinanced their current mortgage to pull out cash for a down payment on their next home, planning to sell the original property within a few months. The new rate ran higher than their old one, but the closing costs were lower than a comparable bridge loan's origination fees — a trade that worked because the sale closed quickly enough to make the short-term rate bump worth it.
For more outcomes like these, see the full client wins and case studies archive, or read client testimonials directly.
Clients who've done exactly this.
Eric and his staff are absolutely the best! Listing photos, brochures, out of state advertising, Eric was on it!
I can't say enough on how smooth everything went from selling one and buying another in less than 30 days, with a triple COE involved. He found me a great home, I let him negotiate the best price, and let me say, saved me double digit thousands — oh, did I mention, managed to get the highest sq. ft. price to date on my Villa that he listed.
Now, that's skill and expertise at work. True professional.
Eric helped us with both ends of the transaction. He helped us find exactly what we were looking for at a price we could afford, and then helped us sell our current home, above our asking price. It could not have worked out better! His professionalism, knowledge, and calm demeanor guided us through the process with ease.
It was a pleasure working with Eric to find a home just fit for my family and I. Eric helped us sell our previous home and find a new home with all our wants and needs. Eric has been great at Communicating with us and listening to our needs. It was a great experience working Eric. Thank you for all your help and patience though out the process!
Like a lot of people we toyed with the idea of just putting up a "for sale" sign and it would be a breeze. Fortunately, we didn't do this and used Eric on a recommendation of a friend. We had lived in our home 27 years and it was in good shape and had desirable qualities, but we quickly found out the process was far more involved than we imagined.
From fixing things pre-sale, getting ready for listing pictures, dealing with showings and inspection, Eric carried us it all. It was a total pain to get to "Sold!" but he helped us every step of the way and was a true professional. We highly recommend Eric and his team.
Being a Realtor myself, I have high standards for anyone I hire. My wife has even tougher standards. We were trying to sell our investment home in Scottsdale (we live in Oregon) and needed to sell it fast in an historically slower moving market. We wanted an agent who would market our home aggressively and strategically, communicate regularly and have well established networks with local trades such as handymen, roofers, electricians, etc. We also wanted a Realtor with a great working network with other busy local agents. On all counts, Eric was a 10 out of 10!
He thoroughly explained his marketing plan and backed it up. He has a system of communication which kept us up to date regularly, so we were never left wondering. Several times in the process, before listing and while in escrow, he had the right contractors out to save the day. An additional perk to our experience with Eric is that, while I at first thought his pricing was crazy, his knowledge and experience in the market proved correct and we netted much more on this sale than I thought was possible!
Eric was always a straight shooter with us; honest, direct, clear and concise. He has earned and holds the Certified Residential Specialist (CRS) designation which only comes with years of experience and education, and it all shows in his professional service. I would absolutely recommend Eric to anyone looking to buy or sell real estate in the Phoenix metro market!
Structuring the offer itself: contingencies
Cheaper than financing, harder to get a seller to accept
Home sale contingency
Your offer depends on selling your current home by a set date. Sellers in competitive markets often pass on these in favor of cleaner offers.
Settlement contingency
A softer version — your offer depends only on an already-signed sale closing, not on finding a buyer. Sellers view this as far less risky.
Kick-out clause
Some sellers accept a home sale contingency but add a window — often 48 to 72 hours — to remove it if a better offer arrives.
Waiving it entirely (non-contingent offer)
Committing to the purchase whether or not your old home has sold — the highest-risk sequence on this list. Protect yourself by lining up backup financing (a bridge loan or HELOC) before you waive it, getting your current home pre-listed or at least market-priced in advance, and confirming you have reserves to cover both payments for several months if the sale takes longer than planned.
In today's Greater Phoenix market, a seller with more than one offer in hand routinely passes over a home-sale contingency in favor of a settlement-only or clean offer — it's rarely a hard no, but it's almost always the tiebreaker. A financing or appraisal contingency is a separate protection and doesn't go away just because you drop the home-sale contingency: if the home you're buying appraises below the contract price, you can still renegotiate, cover the gap in cash, or walk, depending on how that clause is written.
"Can you comfortably carry two mortgage payments for two to four months if your timeline slips? That single question filters most of the noise in this decision."
Instant offers and trade-in programs
Companies that buy homes directly will make a cash offer on your current home, sometimes closing in days, with proceeds available before a traditional sale would even reach closing. Phoenix is one of the most active iBuyer markets in the country — Opendoor and Offerpad both launched here and remain especially active in the valley. The trade-off is priced in: after service fees (commonly around 5% of the offer, on top of typical repair-cost deductions), these offers tend to land roughly 5–10% below what the same home would net on the open market. It's worth it when speed and certainty matter more than maximizing sale price — not when you have the flexibility to list traditionally.
Choosing your path
How much equity do you actually have?
Bridge loans and HELOCs both lean on meaningful equity. Thin equity points toward sell-first with a rent-back.
How fast do homes move in your market?
Fast markets make buy-first tools less risky. Slower markets favor selling first.
How competitive is the home you're buying?
Competitive listings punish contingencies — exactly where a bridge loan or HELOC earns its cost.
Could you cover two payments for a few months?
If the honest answer is no, sell-first is the safer default, full stop.
Want to run your own numbers before we talk? Start with these helpful calculators.
Quick definitions
The shorthand that comes up most in this decision
DTI — Debt-to-Income ratio
Your monthly debt payments divided by your gross monthly income. Lenders use it to size how much mortgage you can qualify for.
LTV — Loan-to-Value ratio
Your loan amount divided by the home's value. A lower LTV — more equity — generally means better rates and more financing options.
PITIA
Principal, Interest, Taxes, Insurance, and Association dues — the full monthly cost lenders use to qualify you, not just principal and interest.
Contingency
A condition in a purchase contract that lets you renegotiate or back out if it isn't met — such as your current home failing to sell by a set date.
Common questions
Is a bridge loan a good idea?
It can be, with strong equity and reasonable confidence your home will sell within the loan term. It's a convenience tool with a real cost, so it tends to make sense when the alternative is losing out on a home you'd otherwise afford.
What's the difference between a home sale and settlement contingency?
A home sale contingency depends on finding a buyer. A settlement contingency depends only on an already-signed sale closing. Sellers view the second as far less risky.
Can I get a HELOC after my home is already listed?
Usually not — most lenders decline once a home is actively on the market. Arrange it before you list, ideally a few months ahead.
Do I still need a lease to use rental income from my old home?
No — as of September 2026, Fannie Mae no longer permits a lease agreement as documentation for departing-residence rental income at all. Market rent from an appraisal (or a market analysis with at least three comparables) is now required instead. That income can only offset the old home's payment, not add to your qualifying income.
Are iBuyer offers worth it?
Worth it if speed and certainty matter more than maximizing price. Offers typically land below open-market value once fees are factored in.
Real estate built on a wealth management foundation
I'm the founder of The Ravenscroft Group at Real Broker — a Top 1% REALTOR® across North America and Top 100 in the Greater Phoenix Metro, recognized as a Platinum Producer (2022–2025) and President's Club recipient (2021–2025). I hold the CRS designation — the highest credential in residential real estate — alongside GRI, ABR, MRP, SRES®, and RSPS.
Before real estate, I served as a Director of Wealth Management, advising clients on timing decisions with real financial consequences. That's exactly what a sell-versus-buy sequencing decision is — which is why I build the financing side of a move as carefully as the search for the home itself. You can read more about my background, or how I approach personal financial planning alongside real estate.
I've closed more than $100 million in residential sales and carry more than 170 five-star Google reviews. My insights on Phoenix real estate and mortgage strategy have been featured in The Wall Street Journal, Morningstar, MarketWatch, MSN Money, and The Residential Specialist. I'm also the host of the House of Ravenscroft Podcast, and I build every transition around a broader real estate financial plan, not just the sale itself.
"Most agents can tell you about a neighborhood. Very few can tell you how to structure the move itself so you're never caught holding two mortgages you can't afford."
The right sequence depends on your equity, your market, and your timeline — not a generic rule of thumb.
That's the part I build with clients — matched to your numbers and the Phoenix-area market you're actually moving in or out of.
Book a Strategy Calleric@theravenscroftgroup.com · (480) 269-5858 · theravenscroftgroup.com
Keep exploring
A few other resources clients use alongside a move like this.
Categories
- All Blogs (319)
- Active Adult & 55 Plus Communities (16)
- Arizona Relocation Guides (29)
- Buyers (210)
- Financial Planning (60)
- General Real Estate (137)
- Income From Real Estate (58)
- Market Update (25)
- New Construction (28)
- News, Updates and Coming Soon (57)
- Real Estate Agent Financial Planning (22)
- Real Estate Investing (93)
- Sellers (106)
- Vacation and Short Term Rentals (45)
Recent Posts

About the Author
Eric Ravenscroft is a Top 1% REALTOR® across North America and one of Arizona’s most trusted real estate strategists. With 15 years of experience spanning real estate, wealth management, and investment planning, he helps clients make smarter, financially grounded decisions, from new construction and relocations to STR investments, 1031 exchanges, and long-term portfolio strategy.
Eric’s expertise has earned him industry recognition, Elite status with Real Broker, and features in major publications including the Wall Street Journal, MarketWatch, MSN, and Morningstar. Clients across the Greater Phoenix Metro rely on his clarity, strategic insight, and results-driven guidance.
Ready to make a confident real estate move? Call or text Eric today.